The consumer artificial intelligence market may be large in usage yet surprisingly narrow in both revenue and product variety. In an October 9 interview with TechCrunch, Andreessen Horowitz partner Olivia Moore argued that much of what the industry currently calls consumer AI is better understood as prosumer software: tools bought by individuals but used for coding, marketing and workplace productivity. Her assessment points to an unresolved question for the sector: whether AI can reach a broad public without depending mainly on subscriptions or business spending.
TechCrunch’s Russell Brandom framed the interview around a new Andreessen Horowitz report on the top 100 consumer AI apps. According to his account, ChatGPT remains far ahead of the field, while services including Suno and ElevenLabs have shown staying power. The report also identifies conspicuous gaps. Moore said its top 100 list contains no entrants in social apps, dating, marketplaces, retail, travel, finance or health—categories that were central to earlier waves of consumer internet growth.
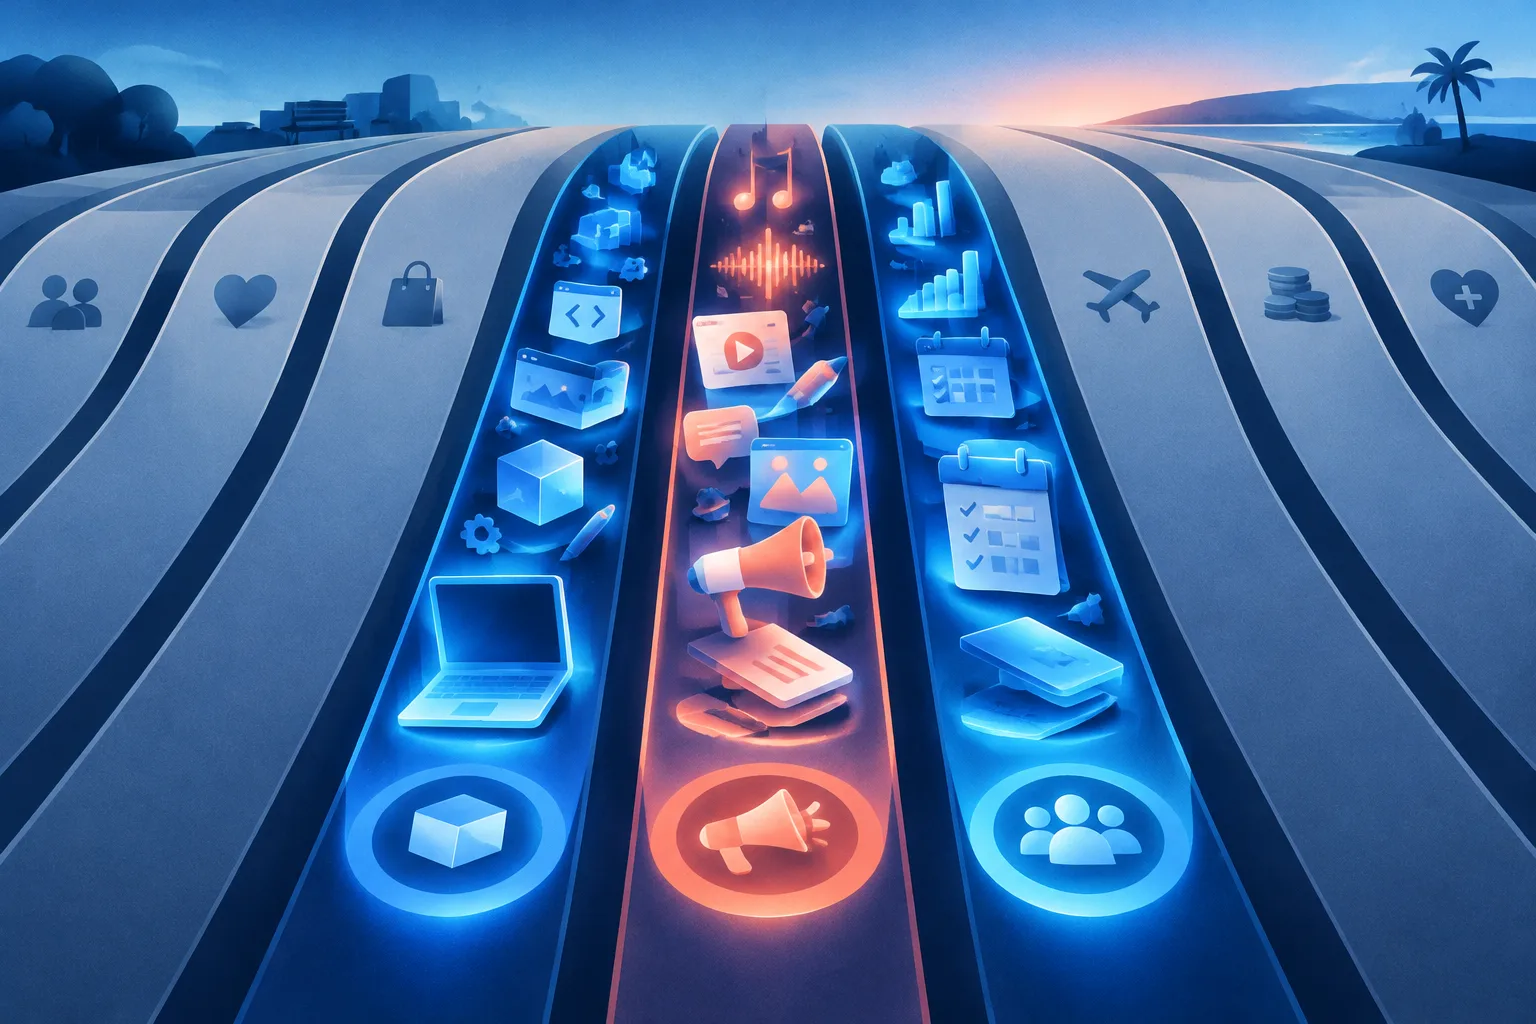
That absence matters because the current revenue base appears concentrated among people using AI for work-like tasks. Moore grouped the strongest spending into product-building applications, product-marketing tools and general work management. She cited companies such as Lovable, Replit and Fal in the first group; Higgsfield and HeyGen in the second; and Manus, Fireflies AI and Granola in the third. In her view, these products may be purchased first by individuals, but they do not resemble the broad consumer services that defined the pre-AI internet.
Moore also described a recurring shift from individual adoption to company sales. She contrasted older consumer-first businesses, which could take years to add team or enterprise plans, with AI companies that move quickly toward organizational customers. As examples, she named Gamma, ElevenLabs and Cursor, saying they began with consumer positioning and became majority-enterprise businesses within 18 months. TechCrunch presented that pattern alongside OpenAI’s renewed emphasis on enterprise customers, though Moore characterized OpenAI’s move as an expansion rather than an abandonment of consumer products.
The economics behind that shift are straightforward in Moore’s telling. She said most AI revenue so far has come from subscriptions and token usage, sources that are concentrated among enterprise and prosumer customers. Citing a State of Markets report, TechCrunch noted that 2.2% of U.S. households pay for AI. Moore did not argue that the industry simply needs to push that figure higher. Instead, she said she is more interested in models that do not require every consumer to pay subscription fees directly.
Advertising is one possibility Moore raised. She argued that many people may prefer free access supported by ads, with subscriptions available to remove them. That option is not costless for providers, because generative AI services have higher marginal costs than classic internet products such as search or social networking. Moore said the pressure could ease through cheaper models and greater use of open-source systems, particularly when a consumer application does not require frontier-level intelligence for every task.
Her case is therefore optimistic but conditional. Moore expects lower-cost models to become more useful as developers build products in which the model is only one component rather than the entire offering. Yet the interview does not establish that advertising will cover inference costs, that untouched consumer categories will produce durable businesses, or that users will accept ads in AI services. Those outcomes remain uncertain. What the report does establish is a mismatch between the label and the market: the most visible consumer AI products are still heavily oriented toward power users and work, while several of the internet’s largest everyday categories remain open terrain.
For builders and investors, the next stage may depend less on creating another general assistant than on discovering products that fit daily consumer behavior and can be delivered cheaply enough to reach large audiences. Moore told TechCrunch that the category is still very early and said she wants to see progress in the missing areas over the next six months. Whether that progress arrives—and whether it creates a business model beyond subscriptions and enterprise expansion—will be a practical test of how consumer-facing the AI boom really is.
Comments
Loading comments…